In 2012, the United States Supreme Court did something remarkable. It upheld a central provision of the Affordable Care Act by determining that a payment Congress called a penalty could constitutionally function as a tax.
Chief Justice John Roberts delivered the deciding opinion in National Federation of Independent Business v. Sebelius. Congress couldn’t force Americans to purchase health insurance under the Commerce Clause, but it could impose a tax consequence for refusing.
Apparently, Washington discovered that when government can’t legally make you do something one way, it might still be able to reach into your wallet another way.
Welcome to constitutional gymnastics.
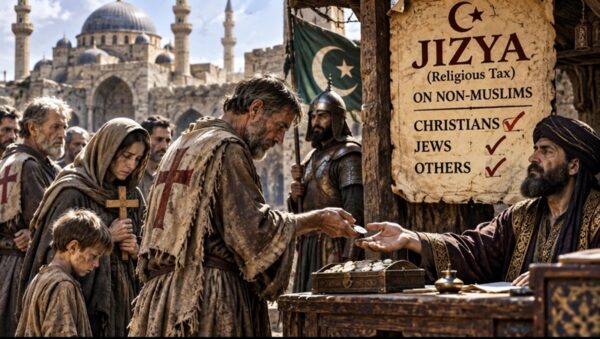
Now consider something most Americans have probably never heard of: jizya.
Historically, jizya was a tax imposed upon certain non-Muslims, particularly Christians and Jews, living under Islamic governments. It formed part of the dhimmi system, which offered protected religious status while imposing various legal restrictions.
Muslims had their own financial religious obligations, including zakat. But jizya was different. Liability for the tax was explicitly connected to being a non-Muslim subject.
Depending upon the historical government, payment could be associated with exemptions from military service and other obligations. Nevertheless, the underlying distinction remained religious.
Now imagine this scenario.
A future American Congress passes legislation requiring citizens who refuse to follow a particular religion to pay an annual religious accommodation tax.
Let’s call it $1,000.
Don’t believe in the government’s preferred religion? Congratulations. Your freedom of conscience now comes with an invoice.
Could Congress defend that law by pointing to the Affordable Care Act decision?
Almost certainly not. And understanding why matters.
The Supreme Court’s ACA ruling recognized Congress’s substantial taxing authority. It did not grant Congress permission to violate the First Amendment.
The Establishment Clause prohibits government from establishing religion. The Free Exercise Clause protects religious practice. Constitutional equal-protection principles provide additional safeguards against religious discrimination.
A tax imposed simply because someone is Christian, Muslim, Jewish, or atheist would encounter enormous constitutional obstacles.=
And that protection works both ways.
An Islamic government cannot constitutionally impose a special tax on American Christians for refusing Islam. Neither can a Christian government impose one on American Muslims for refusing Christianity.
That’s not religious favoritism.
That’s constitutional government.
But here’s the larger question Americans ought to consider.
How much influence over individual liberty should government possess through its power to tax?
The ACA decision demonstrated that taxation can influence conduct even when Congress lacks authority to command that conduct directly under the Commerce Clause.
That principle is significant.
Taxes can encourage certain decisions, discourage others, and influence economic behavior. Congress has employed financial incentives throughout American history.
But there’s a constitutional boundary between influencing ordinary economic decisions and punishing protected religious beliefs.
Cross that boundary and government ceases merely collecting revenue. It begins attempting to regulate conscience.
And conscience is precisely what the First Amendment was designed to protect.
Now consider the broader issue of religious authoritarianism.
Osama bin Laden and al-Qaeda advocated replacing existing political systems with their extremist interpretation of Islamic governance. Their objective was not constitutional pluralism but a transnational caliphate.
That ideology is not representative of every Muslim, nor does ordinary Islamic religious observance threaten American constitutional government.
The constitutional concern arises when anyone seeks to convert religious doctrine into compulsory governmental authority over unwilling citizens.
Whether the instrument is a criminal statute, religious tribunal, financial penalty, or discriminatory tax, the underlying issue is the same.
Who possesses ultimate legal authority in America: the Constitution or a religious institution?
Article VI already answers that question.
The Constitution and laws made pursuant to it are the supreme law of the land.
Religious authorities may guide willing believers. They cannot supersede American constitutional rights.
Which brings us to the uncomfortable conclusion.
America probably doesn’t need another constitutional amendment to prohibit a religious tax resembling jizya. Existing constitutional protections already provide substantial defenses.
What America needs is an informed citizenry that understands the difference between legitimate taxation and unconstitutional religious coercion.
Because the danger isn’t that every tax becomes tyranny.
The danger is forgetting that even legitimate governmental powers have constitutional limits.
The government may have authority to tax your choices. It does not thereby acquire authority to tax your conscience.
And if Americans ever forget that distinction, the problem won’t be a shortage of constitutional amendments.
It will be a shortage of Americans who understand the Constitution they inherited.
If you enjoyed this article, then please REPOST or SHARE with others; encourage them to follow AFNN. If you’d like to become a citizen contributor for AFNN, contact us at managingeditor@afnn.us Help keep us ad-free by donating here.
Substack: American Free News Network Substack
Truth Social: @AFNN_USA
Facebook: https://m.facebook.com/afnnusa
Telegram: https://t.me/joinchat/2_-GAzcXmIRjODNh
Twitter: https://twitter.com/AfnnUsa
GETTR: https://gettr.com/user/AFNN_USA
CloutHub: @AFNN_USA